Anti-Money Laundering is a broad subject, with a significant amount of terminology that needs to be understood to fully engage with it and recognise your obligations under UK law.
At Amiqus, we help regulated organisations complete AML checks swiftly and securely online. In this article, we’ll explain common UK AML terms in plain English, covering the checks, legislation, organisations, and processes you’re likely to encounter.
Key Anti-Money Laundering terminology
Anti Money Laundering (AML)
Anti Money Laundering (AML) refers to the laws, regulations, and processes designed to prevent criminals from disguising the proceeds of crime as legitimate funds. UK-regulated businesses need appropriate systems and controls to identify and manage money laundering risks.
Know Your Customer (KYC)
Know Your Customer (KYC) describes the processes used to establish and verify who a customer is. It can involve confirming identity, address, ownership, and other information needed to understand who you’re doing business with.
Customer Due Diligence (CDD)
Customer Due Diligence (CDD) involves identifying a customer and verifying their identity using reliable, independent information. Depending on the circumstances, it can also include identifying beneficial owners and understanding the purpose and intended nature of a business relationship.
Enhanced Due Diligence (EDD)
Enhanced Due Diligence (EDD) means carrying out additional measures when higher money laundering or terrorist financing risks are identified. The extent of these checks should reflect the risks involved. UK regulations also specify circumstances in which enhanced measures are required.
Simplified Due Diligence (SDD)
Simplified Due Diligence (SDD) allows regulated businesses to apply less extensive measures where the relationship or transaction presents a lower risk. It doesn’t mean skipping due diligence. Businesses still need to assess the risk and meet applicable requirements.
Risk-based approach
A risk-based approach means identifying and assessing money laundering and terrorist financing risks, then applying controls that reflect them. UK AML requirements place an emphasis on using risk to determine the appropriate level of due diligence.
Risk assessment
A risk assessment identifies the financial crime risks associated with a customer, transaction, or business relationship. Factors can include the customer, geographic location, services provided, and how the relationship is conducted.
Politically Exposed Person (PEP)
A Politically Exposed Person (PEP) is someone entrusted with a prominent public function. UK requirements also consider relevant family members and known close associates. Regulated businesses need to assess PEP risk on a case-by-case basis and apply appropriate measures.
Adverse media
Adverse media is negative information about an individual or organisation found in credible news and media sources. Relevant findings can help identify potential financial crime risks and indicate when further investigation may be appropriate.
Ultimate Beneficial Owner (UBO)
An Ultimate Beneficial Owner (UBO), or beneficial owner, is the individual who ultimately owns or controls a business or legal entity, even where ownership is held indirectly through other companies or arrangements. Identifying the UBO helps your team understand who ultimately benefits from or exercises control over the organisation you’re dealing with.
Person with Significant Control (PSC)
A Person with Significant Control (PSC) is an individual who meets specified conditions relating to the ownership or control of a UK company. PSC information can help organisations understand company structures as part of their due diligence.
Source of funds
Source of funds describes where the money for a particular transaction or business relationship comes from. Checking the source of funds can help your team establish whether the origin of the money is consistent with what you know about the customer.
Source of wealth
Source of wealth looks at how someone accumulated their overall wealth, rather than where the money for one transaction came from. It can be relevant when carrying out Enhanced Due Diligence and assessing higher-risk relationships.
Identity verification
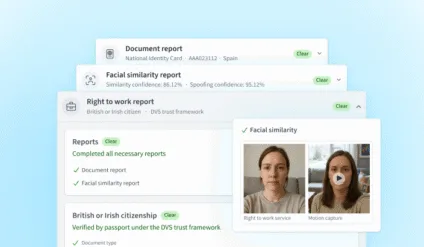
Identity verification is the process of confirming that someone is who they claim to be. Digital identity verification can use identity documents and other information to help organisations complete this process remotely.
Address verification
Address verification helps confirm a customer’s residential address using reliable information or data sources. It can form part of the information gathered during onboarding and due diligence.
Ongoing monitoring
Ongoing monitoring means reviewing a business relationship over time. This includes keeping due diligence information up to date and scrutinising activity where appropriate, rather than treating AML compliance as a one-off check at onboarding.
Suspicious Activity Report (SAR)
A Suspicious Activity Report (SAR) provides information to the National Crime Agency about suspected money laundering or terrorist financing. Relevant organisations need processes for identifying, escalating, and reporting suspicions where required under UK law.
Money Laundering Reporting Officer (MLRO)
A Money Laundering Reporting Officer (MLRO) is responsible for overseeing relevant AML processes within an organisation. Responsibilities can include receiving internal reports of suspicious activity and considering whether a SAR needs to be submitted.
Audit trail
An audit trail records the checks, evidence, actions, and decisions involved in a compliance process. A clear record helps your team understand what was done, when it happened, and how a decision was reached.
Open Banking
Open Banking allows customers to securely share financial information with authorised providers. It can support processes such as source of funds checks by providing access to relevant financial information with the customer’s permission.
Financial Action Task Force (FATF)
The Financial Action Task Force (FATF) sets international standards for combating money laundering, terrorist financing, and proliferation financing. Its recommendations influence AML frameworks around the world, including the UK’s risk-based approach.
Office of Financial Sanctions Implementation (OFSI)
The Office of Financial Sanctions Implementation (OFSI), part of HM Treasury, supports the implementation and enforcement of UK financial sanctions. It provides guidance, carries out enforcement activity, and administers financial sanctions licensing.
UK Financial Intelligence Unit (UKFIU)
The UK Financial Intelligence Unit (UKFIU) sits within the National Crime Agency. It receives, analyses, and distributes financial intelligence gathered through SARs, supporting the UK’s response to money laundering and other financial crime.
National Crime Agency (NCA)
The National Crime Agency (NCA) is the UK law enforcement agency responsible for tackling serious and organised crime. Its responsibilities include tackling money laundering and illicit finance, with the UKFIU operating within the NCA.
Money Laundering Regulations (MLRs)
The Money Laundering Regulations (MLRs) set out important AML and counter-terrorist financing requirements for businesses in the UK regulated sector. The current framework is based on the Money Laundering, Terrorist Financing and Transfer of Funds Regulations 2017, as amended.
Proceeds of Crime Act 2002 (POCA)
The Proceeds of Crime Act 2002 (POCA) is a central part of the UK’s legislation for tackling money laundering and recovering the proceeds of crime. Among other provisions, it establishes principal money laundering offences and requirements relevant to reporting suspected criminal property.
Defence Against Money Laundering (DAML)
A Defence Against Money Laundering (DAML) can be requested through the SAR process in circumstances where a person or organisation has identified suspected criminal property and an intended activity could otherwise amount to a principal money laundering offence under POCA. Whether a DAML is required depends on the circumstances and relevant legal requirements.
Why clear AML terminology matters
AML requirements are detailed, but explaining them doesn’t need to be complicated. Understanding the terminology helps your team know what different checks are for, where responsibilities sit, and when additional steps may be needed.
Clear language can make the process easier for clients, too. Requests for identity documents or financial information can be sensitive. Explaining what you need and why you need it gives clients a clearer view of the process while helping your team collect the information required.
Technology can then help you put those requirements into practice. Bringing checks, results, supporting evidence, and progress together reduces unnecessary handoffs and gives your team a clearer view of each client’s onboarding journey.
Manage Anti Money Laundering compliance with Amiqus
Understanding AML terminology makes it easier to navigate the processes behind effective compliance. From Customer Due Diligence and identity verification to source of funds and ongoing monitoring, each part contributes to a clearer picture of the clients you work with and the risks you need to manage.
At Amiqus, we help regulated organisations manage AML checks securely online, bringing key parts of client onboarding into one place. If you want to reduce manual admin, keep your compliance processes consistent, and make onboarding easier for your team and clients, get in touch today.